How to Check Your CRB Status in Kenya for Free and Clear Your Name
You're entitled to a free credit report from each CRB every year, and your first clearance certificate is free. How to check Metropol, TransUnion and Creditinfo, dispute errors and clear a listing.

In this guide▾
- How do I check my CRB status in Kenya?
- The three bureaus and how to reach them
- How to read your report
- If you've been listed: how to clear your name
- When the listing is wrong: how to dispute it
- Mobile loans and your CRB record
- Habits that build a strong record
- A note on the regulations
- Frequently asked questions
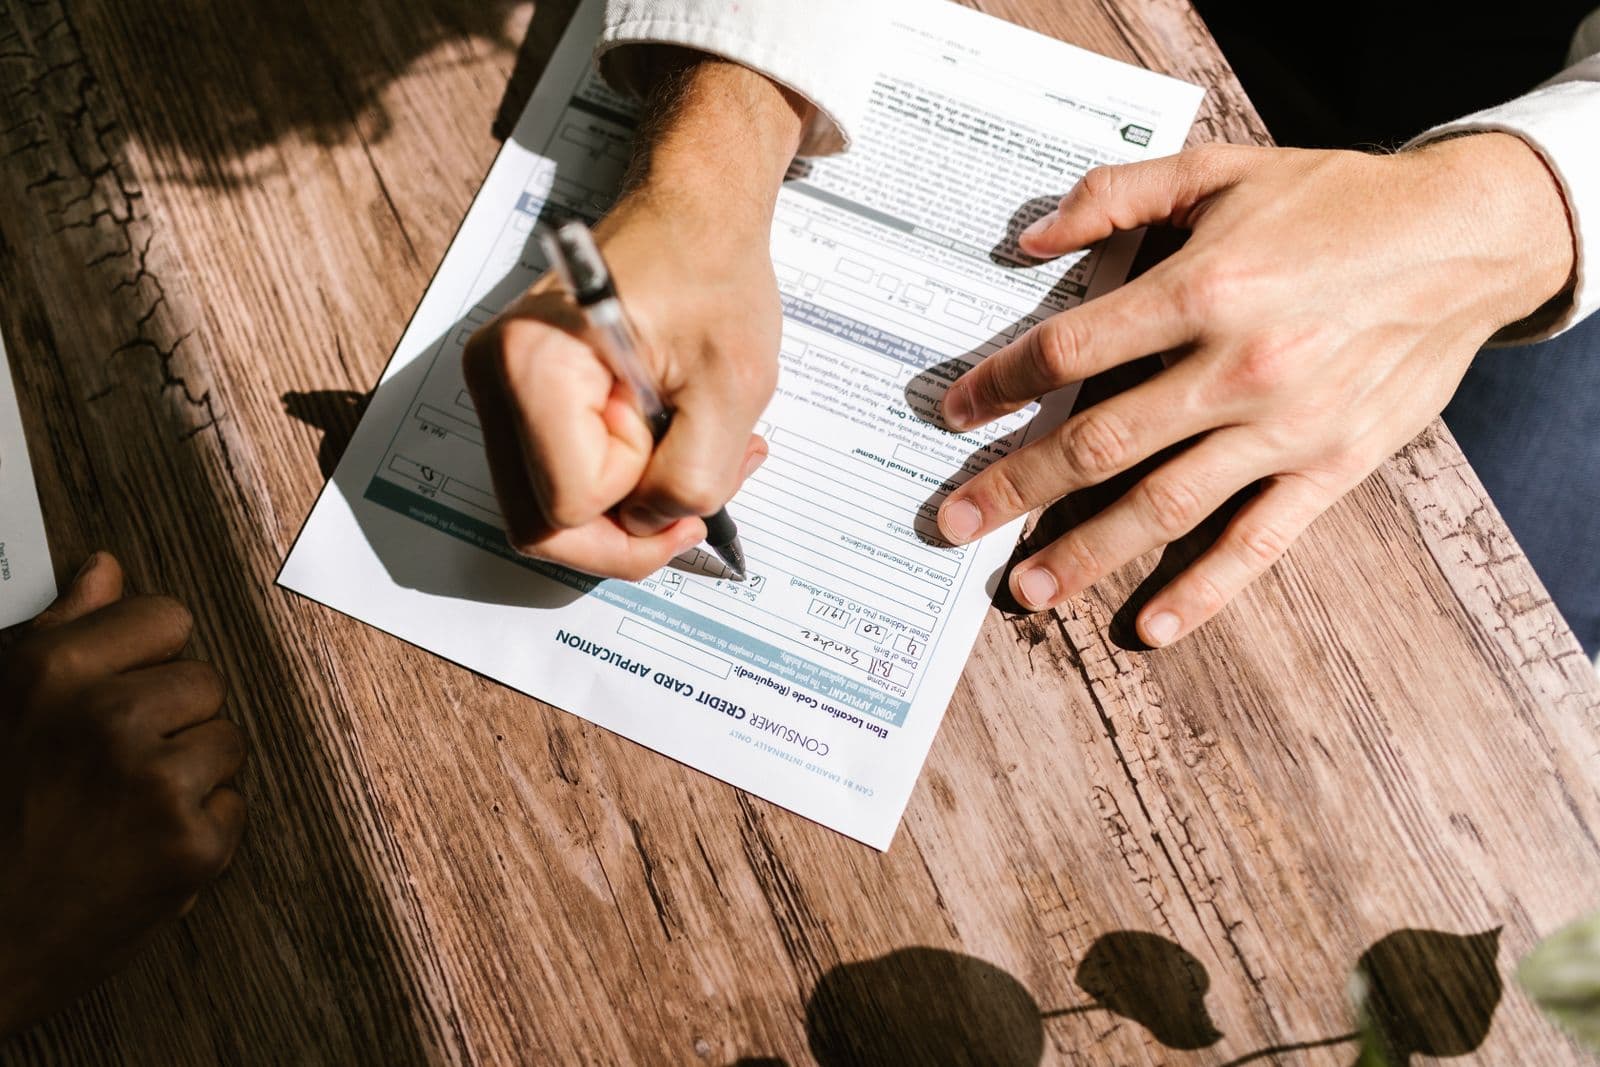
A loan app turns you down, a bank asks for a clearance certificate, or a job offer wants proof you're not blacklisted. All of these come down to your record at a credit reference bureau (CRB). You can see that record yourself, and once a year it's free.
Being "on CRB" isn't always bad. The bureaus hold your good repayment history too, and that's what earns you bigger loans at better rates.
| Your rights under Kenya's CRB rules | What the regulations say |
|---|---|
| Licensed bureaus | Metropol, TransUnion and Creditinfo |
| Free credit report | At least once a year from each bureau, within 30 days of being refused credit, and every 6 months after you dispute an error |
| How fast you get it | Within 5 working days of asking |
| Small debts | Negative information of KES 1,000 or less can't be reported |
| Warning before listing | The lender must tell you at least 30 days before reporting you |
| How long a default stays | 5 years from the date you finally settle it |
| Clearance certificate | Your first one is free |
| Disputes | The bureau flags the entry within 5 working days; the lender has 21 days to investigate |
Source: the Banking (Credit Reference Bureau) Regulations, 2020, checked November 2026.
How do I check my CRB status in Kenya?
Register with each of the three licensed bureaus (Metropol, TransUnion and Creditinfo) using your ID, through their app, USSD code or website, and request your credit report. The law entitles you to one free report a year from each bureau. The report shows every loan, whether you paid on time, any default and the lender that reported it.
The three bureaus and how to reach them
| Bureau | How to check |
|---|---|
| Metropol | Dial *433# or use the Crystobol app |
| TransUnion | Its Nipashe service, through the app or website |
| Creditinfo | Register and request your report at creditinfo.co.ke |
Each bureau gets data from the lenders that report to it, so the three reports can differ. Check all three, especially before applying for a big loan or mortgage. Beyond your free yearly reports, extra checks may cost a small fee.
How to read your report
Your report has a credit score and a list of your credit accounts. For each one you'll see the lender, the amount, the dates and the repayment status.
- Positive information: loans paid on time. This helps you.
- Negative information: loans in default. For banks, a loan becomes non-performing once a payment is more than 30 days overdue.
- The lender's name appears on every negative entry, so you know who to deal with.
A CRB can't stop you getting a loan on its own. The regulations say a credit score alone can't be used to refuse you credit. Lenders still look at it closely, though.
If you've been listed: how to clear your name
- Find out who listed you and for how much. It's on the report.
- Pay or negotiate. Settle the full amount, or agree a payment plan in writing with the lender.
- Get a settlement letter once the balance is cleared.
- Make sure the lender updates the bureaus. The listing changes to "settled". It doesn't disappear: the record stays for 5 years from the settlement date, but a settled default looks far better to lenders than an open one.
- Request a clearance certificate. Your first one is free from each bureau.
Ignore anyone who offers to "remove your name from CRB" for a fee. Only the lender's update or a successful dispute changes your record.
When the listing is wrong: how to dispute it
Mistakes happen: a loan you already paid, a debt that isn't yours, or a loan taken out in your name after a SIM swap.
- Write to the bureau, explaining what's wrong and attaching proof such as receipts or M-Pesa statements.
- Within 5 working days, the bureau must flag the entry as under investigation.
- The lender has 21 days to investigate and tell all the bureaus whether to delete, correct or keep the entry.
- If it's wrong, every bureau must fix it and inform anyone affected.
- Still unhappy? You can take the dispute to alternative dispute resolution, the courts or the Central Bank of Kenya.
You're also entitled to a free report every 6 months after asking for a correction, so you can check it was fixed.
Mobile loans and your CRB record
Licensed digital lenders, Fuliza, M-Shwari and bank mobile loans all report to the CRBs. The KES 1,000 rule protects you on tiny loans: a default of KES 1,000 or less can't be reported as negative.
Larger mobile loans count. A KES 3,000 Fuliza balance left unpaid for months can block a much bigger loan later. If you use Fuliza or mobile loans, clear them first when money is tight, and only borrow from licensed loan apps.
Habits that build a strong record
- Pay a day early, not a day late. Automatic repayments help.
- Borrow less than you're offered. Using every shilling of a limit looks riskier.
- Keep one or two loans going well rather than juggling many apps.
- Check your three reports once a year, using your free entitlement, and dispute errors quickly.
A note on the regulations
The 2020 CRB regulations were challenged in court. The High Court annulled them in 2023, and the Court of Appeal reinstated them. They're the rules in force, but follow any later court decision.
Frequently asked questions
Is checking your CRB status free in Kenya?
Yes, once a year from each of the three bureaus. You're also entitled to a free report within 30 days of being refused credit and every 6 months after disputing an error. Extra checks may cost a small fee.
How long does a CRB listing last in Kenya?
Negative information stays for 5 years from the date you finally settle the debt. The sooner you settle, the sooner the 5 years start.
Can I get a loan if I'm listed on CRB?
Possibly. A credit score can't be the only reason a lender refuses you, but most lenders will hesitate while a default is unpaid. Settle it, then build a clean record.
How much is a CRB clearance certificate?
Your first clearance certificate from each bureau is free. Later certificates may cost a fee set by the bureau.
Can a lender list me on CRB without telling me?
No. The lender must notify you at least 30 days before submitting negative information, unless your loan contract sets a shorter notice period.
Keep reading
Do Kenyans Abroad Pay Tax to KRA? Residency, Rent and Filing
Your salary abroad is usually safe from KRA, but rent from a Kenyan property is taxed at 30%. The residency tests, monthly rent tax and how to file from abroad.
20 Nov 2026 · 9 min read
KRA Tax Compliance Certificate: How to Apply, Verify and Fix a Rejection
A KRA tax compliance certificate is free, lasts 12 months and is emailed at once if your taxes are clean. How to apply on iTax, the eTIMS rule, why applications are rejected and how to fix them.
18 Nov 2026 · 5 min read
Black Friday 2026 in Kenya: Dates, Jumia Deals and How to Spot a Fake Discount
Black Friday 2026 in Kenya is on 27 November, and Jumia's sale runs all month. How to check a discount is real, verify a phone and pay safely.
18 Nov 2026 · 5 min read